Roofing
Missing, lifted, creased, punctured, or displaced roof materials.
Storm & Wind Claim Help
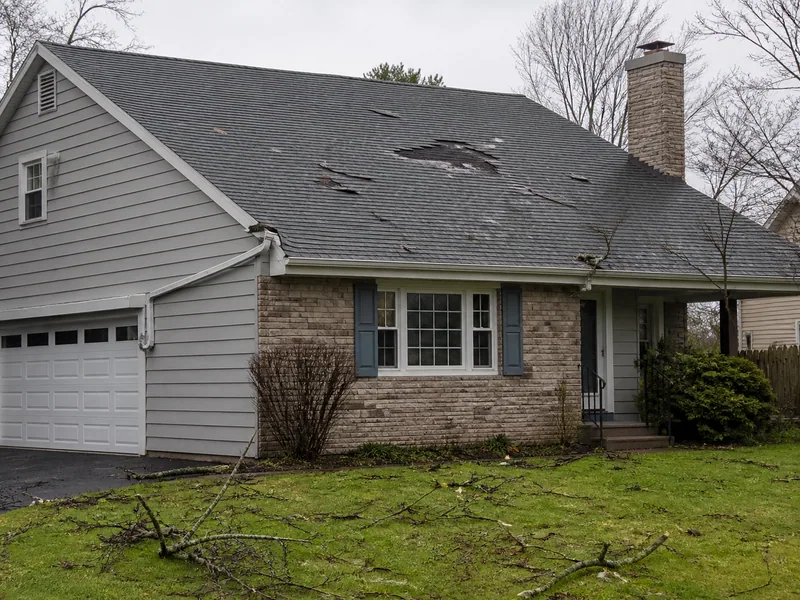
Wind and severe weather can damage roofing and exteriors while allowing water into walls and ceilings. We help connect the exterior event to the complete documented repair scope.
Understand the Full Loss
Some storm damage is obvious, such as missing shingles or a fallen limb. Other conditions, including lifted roofing, damaged flashing, or wind-driven openings, may require a closer inspection and a timeline tied to the event.
A claim may involve exterior repairs, interior water damage, temporary protection, and detached structures. Coverage depends on the cause of loss, exclusions, deductibles, and other policy terms.
See how our public adjuster services work Damage Scope
Missing, lifted, creased, punctured, or displaced roof materials.
Cracked, detached, dented, or wind-damaged exterior cladding.
Broken glass, damaged frames, seals, or surrounding finishes.
Detached, bent, or impact-damaged drainage components.
Ceiling, wall, insulation, and flooring damage after an opening.
Tree impact and damage to garages, sheds, fences, or other insured structures.
Policyholder Support
We help turn the observed storm and wind damage into an organized claim file. The work is evidence-based and tied to the policy; it does not guarantee coverage or a particular payment.
Build the Record
Every useful record should connect to the damaged property, repair need, or applicable claim expense.
How We Work
Each claim is different. These steps keep the storm and wind damage claim documentation and communication organized.
Tell us what happened. We review your claim and your policy at no cost and with no obligation.
We inspect the property and document the full extent of the damage.
We organize estimates, documentation, inventories, and supporting evidence.
We communicate and negotiate with the insurance company on your behalf.
We work toward a fair settlement based on your documented loss and your policy.
Existing Claim Questions
The cause may be attributed to age rather than a specific weather event.
Repair areas, accessories, or related components may be disputed.
Exterior repairs may be listed without the resulting interior work.
Existing siding or roofing may no longer be readily available.
Removal, temporary protection, and building repairs may be treated separately.
One cause or portion of the loss may be accepted while another is questioned.
Already received a decision or payment? Review our denied and underpaid claim help.
Why Property Owners Call
Our role is to prepare and present the policyholder's property claim.
Service is centered on residential and commercial claims throughout the state.
We connect conditions, measurements, estimates, and records to the claimed loss.
We keep the documentation and insurer correspondence organized through the process.
Statewide Service
Explore city-specific claim help or contact us if your community is not listed.
View all New Jersey service areasQuestions From Property Owners
Answers are general. Coverage, deadlines, and claim options depend on the policy and facts.
As soon as conditions are safe. Prompt photographs and a qualified inspection can help connect damage to the event before temporary repairs or later weather alter it.
Yes. Lifted, creased, or displaced materials may be less visible from the ground. A safe inspection is important.
It may be when tied to a covered storm-created opening or other covered cause. The policy and evidence control.
Age and storm damage can be disputed together. We can help document observed conditions, the event, and the proposed repair scope.
Yes. We can review the estimate and compare it with the documented exterior and interior damage.
Flood and storm-surge losses may require separate coverage. We do not assume coverage without reviewing the policy and cause of loss.
Free Consultation • No Obligation
Tell us what happened and where the claim stands. We’ll explain how a public adjuster may be able to help.